
Education expenses are a recurring part of many peoples lives, whether for initial degrees, certifications, or continuing professional development.
Planning ahead helps reduce stress when bills arrive and keeps learning goals on track.
A clear budget turns vague intentions into actionable steps you can follow each month.
This article outlines practical approaches to assess costs, prioritize spending, and build flexible funding plans.
Assess Current and Future Education Costs
Begin by listing direct and indirect costs associated with the learning goal, such as tuition, books, materials, travel, and lost income during study periods. Include recurring fees and one-time expenses, and estimate how costs may change over time due to inflation or program changes. Research typical expenses for similar learners or programs to ground your estimates in reality. This assessment creates the baseline needed to build a pragmatic budget.
Next, map costs to a timeline so you know when major payments are due and how long you need to save. Having realistic dates prevents surprise shortfalls and makes financing decisions easier.
Build a Realistic, Flexible Budget
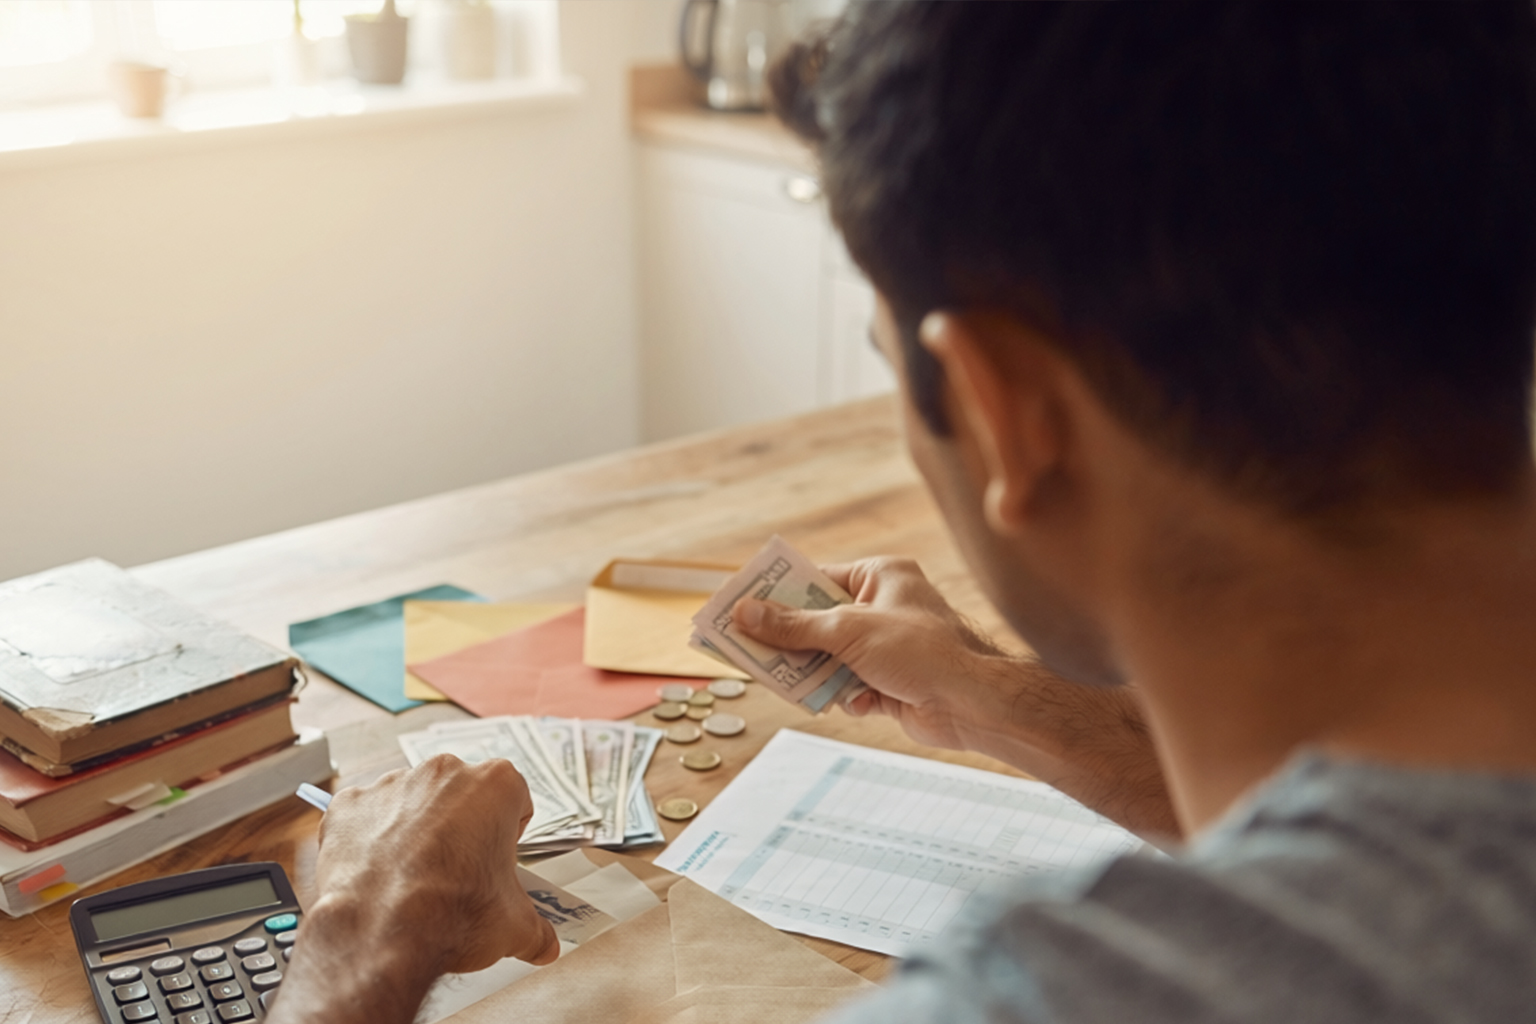
Create a monthly budget that allocates funds for education alongside living costs, savings, and emergency reserves. Prioritize essential items first, then determine how much can go toward education without compromising financial stability. Small, consistent contributions to a dedicated education fund can reduce the need for expensive loans. Adjust the budget quarterly to reflect changes in income, expense patterns, or program timelines.
- Set a target monthly contribution based on your timeline.
- Keep a small buffer for unexpected course fees or materials.
- Automate transfers to your education savings when possible.
Maintaining discipline and flexibility together helps you stay on track while accommodating life’s variability.
Explore Funding Options and Cost-Saving Strategies
Investigate scholarships, grants, employer tuition assistance, and tax-advantaged accounts that can offset costs without adding debt. Compare loan terms carefully if borrowing is necessary, and consider part-time study or online options that reduce living or commuting expenses. Reusing resources like secondhand textbooks, open educational resources, and library access can cut material costs significantly. Peer networks and alumni groups often share tips and cost-saving opportunities relevant to your program.
Combining funding sources and cost-conscious habits reduces reliance on any single option and increases long-term resilience.
Conclusion
Practical budgeting for education starts with clear cost assessment and a realistic timeline.
Build a flexible monthly plan, seek alternative funding, and adopt simple cost-saving habits.
Consistent effort and small adjustments make learning affordable without jeopardizing financial health.