
Education costs creep into household budgets in small bursts: textbooks, course fees, travel, or unexpected certification renewals. Left unchecked those small items add up and push families into last-minute borrowing or skipped opportunities. A few practical habits, applied consistently, can make spending predictable and reduce the need for drastic trade-offs. This article lays out straightforward steps to keep learning affordable without sacrificing quality.
Build a realistic, rolling education budget
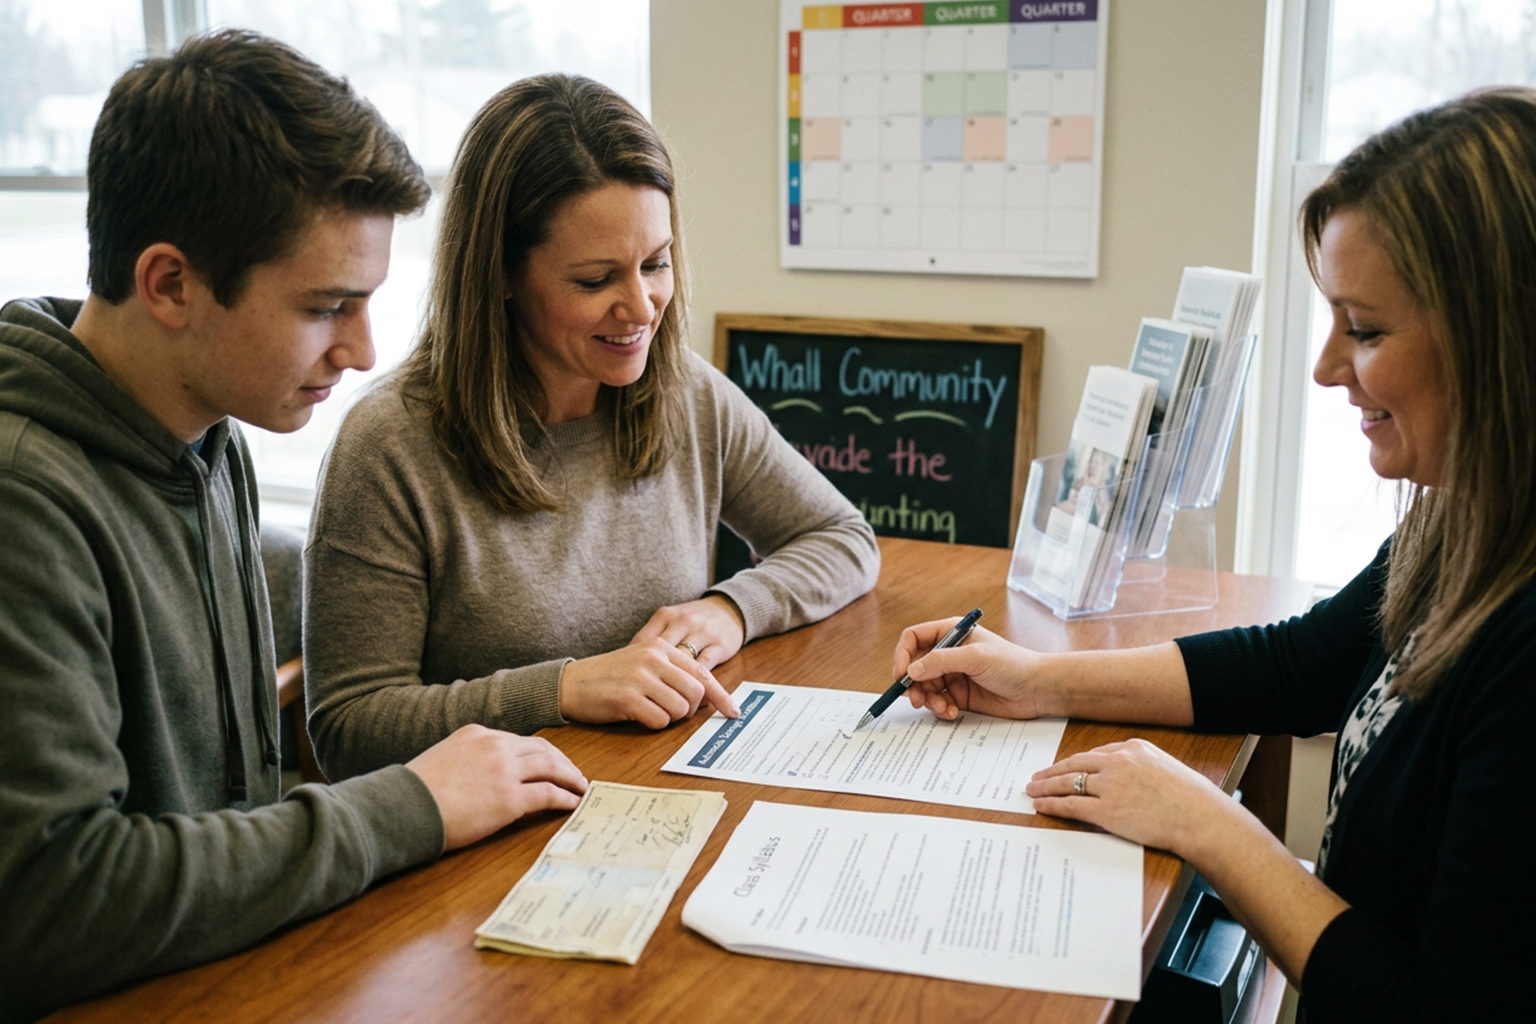
Start by mapping what you or your family spends on learning over the past year: tuition, materials, subscription services, and exam fees. Group items into predictable categories and estimate quarterly costs rather than a single annual target to smooth out peaks. Keep a dedicated line in your household budget for education so those charges are visible, not buried among other expenses. Updating that figure each quarter helps you react to new needs without panic.
When a course or program appears, compare its price against your rolling budget before you commit. If it exceeds what you planned, delay or find a lower-cost alternative rather than tapping emergency credit. Small, consistent checks prevent surprises and preserve your options.
Shift spending toward high-value, lower-cost choices
Not every learning opportunity requires the steepest price tag. Evaluate courses by outcomes — what skills or credentials you gain — rather than brand or duration alone. Look for alternatives that deliver the same core benefits at a fraction of the cost. That can mean community classes, accredited online programs, or employer-subsidized training.
- Use used or digital textbooks instead of new print editions.
- Choose certificates with clear career impact over lengthy degrees when appropriate.
- Apply early for scholarships, fee waivers, or employer tuition assistance.
Small shifts in where you spend can free up money for higher-impact learning later. Prioritizing return on investment keeps quality high and costs controlled.
Automate savings and protect flexibility
Set up an automatic transfer to a designated education account each payday, even a modest amount builds up over time and reduces the urge to borrow. Keep funds in liquid, low-fee accounts so they’re available for unpredictable needs like certification renewals or short intensive courses. Avoid locking everything into accounts with penalties; flexibility matters when opportunities arise.
Combine automatic savings with a regular review: quarterly checks reveal whether your plan aligns with changing goals. When goals shift, reallocate saved funds rather than starting from zero.
Conclusion
Consistent small habits—budgeting, choosing cost-effective options, and automating savings—make education spending manageable. They reduce surprises and keep learning opportunities open without high-interest debt. Start with one change today and build from there.