
Education expenses can feel overwhelming without a clear plan, whether for primary learning or advanced studies. Understanding the full scope of costs helps families and learners make informed choices about priorities and timing. This article outlines practical steps to estimate, prepare for, and reduce education-related spending while preserving flexibility. It emphasizes proactive planning, realistic budgeting, and exploring funding options.
Assessing Education Costs
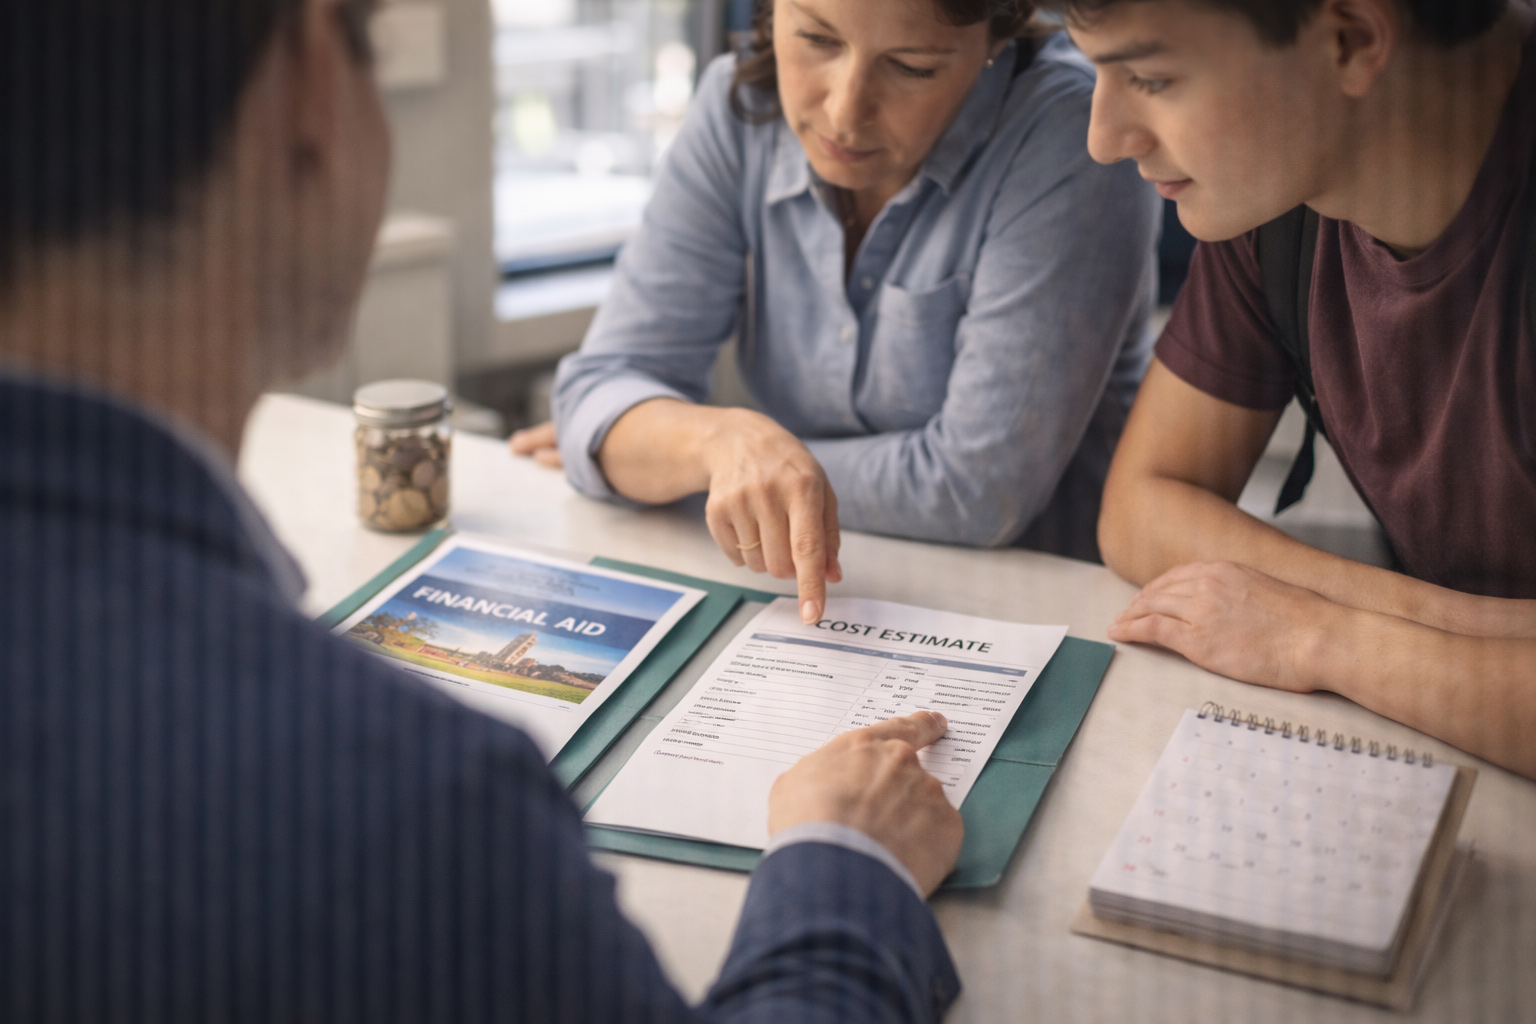
Begin by listing all likely expenses: tuition, fees, books, technology, travel, and living costs if applicable. Include less obvious items such as extracurriculars, testing fees, and transportation to avoid surprises. Use recent bills and school estimates to create a baseline and update it annually as prices change. When possible, model multiple scenarios—conservative, moderate, and optimistic—to gauge the funding gap.
A clear, itemized estimate reduces uncertainty and focuses your savings or funding plan. This foundation makes other decisions, like borrowing or cutting discretionary costs, more data-driven.
Creating a Flexible Budget
Design a budget that separates fixed commitments from flexible spending to preserve options during unforeseen changes. Allocate a target monthly or yearly contribution toward education and protect that amount in a dedicated account. Factor in inflation and potential tuition increases by adding a buffer percentage to your estimates each year. Prioritize high-impact categories like tuition and required supplies before discretionary activities.
Review the budget quarterly and adjust contributions as income or circumstances shift. Flexibility prevents last-minute debt and supports steady progress toward goals.
Maximizing Funding and Savings
Explore all funding sources early: scholarships, grants, tax-advantaged savings plans, employer benefits, and work-study opportunities. Apply for scholarships broadly and renew applications regularly, as awards can offset a sizable portion of costs. Consider a dedicated savings vehicle that offers growth and easy access when needed, balancing risk and liquidity. Investigate institutional aid policies and meet application deadlines to improve eligibility.
Diversifying funding reduces reliance on loans and eases short-term cash pressure. Combining small sources can add up to meaningful financial relief.
Managing Debt and Payments
If borrowing is necessary, compare loan terms, interest rates, and repayment options carefully before accepting offers. Prefer loans with flexible repayment plans, clear deferment policies, and borrower protections when available. Keep borrowing to the minimum required by balancing current savings, income, and part-time work opportunities. Maintain clear records of all loans and set reminders for payments to avoid penalties.
Strategic borrowing preserves future financial options and avoids excessive interest costs. Plan for repayment alongside other long-term goals like housing or retirement.
Conclusion
Building a sustainable plan for education costs reduces stress and supports better outcomes for learners and families. By assessing expenses, budgeting flexibly, maximizing funding, and managing borrowing wisely, you can control the financial impact of education. Begin small, review often, and adjust strategies as circumstances evolve.