
Planning for education expenses can feel overwhelming, but a clear, flexible approach reduces uncertainty. Start by estimating likely costs and listing priorities so decisions reflect values rather than pressure. Knowing timelines and potential funding shortfalls early creates breathing room to explore options. This article outlines practical steps to balance savings, aid, and smart spending.
Assessing Costs and Priorities
Begin with a realistic estimate of tuition, fees, supplies, and living expenses across the expected timeline. Break costs into must-have and nice-to-have categories to identify where adjustments are possible without undermining educational goals. Consider return on investment for different programs and how long-term outcomes align with family or personal priorities. Having prioritized costs helps target resources and reduces reactive decisions later.
Reviewing priorities periodically keeps the plan relevant as circumstances change. Regular reassessment allows reallocation toward higher-impact areas and prevents sunk-cost thinking from dominating choices.
Flexible Funding Options
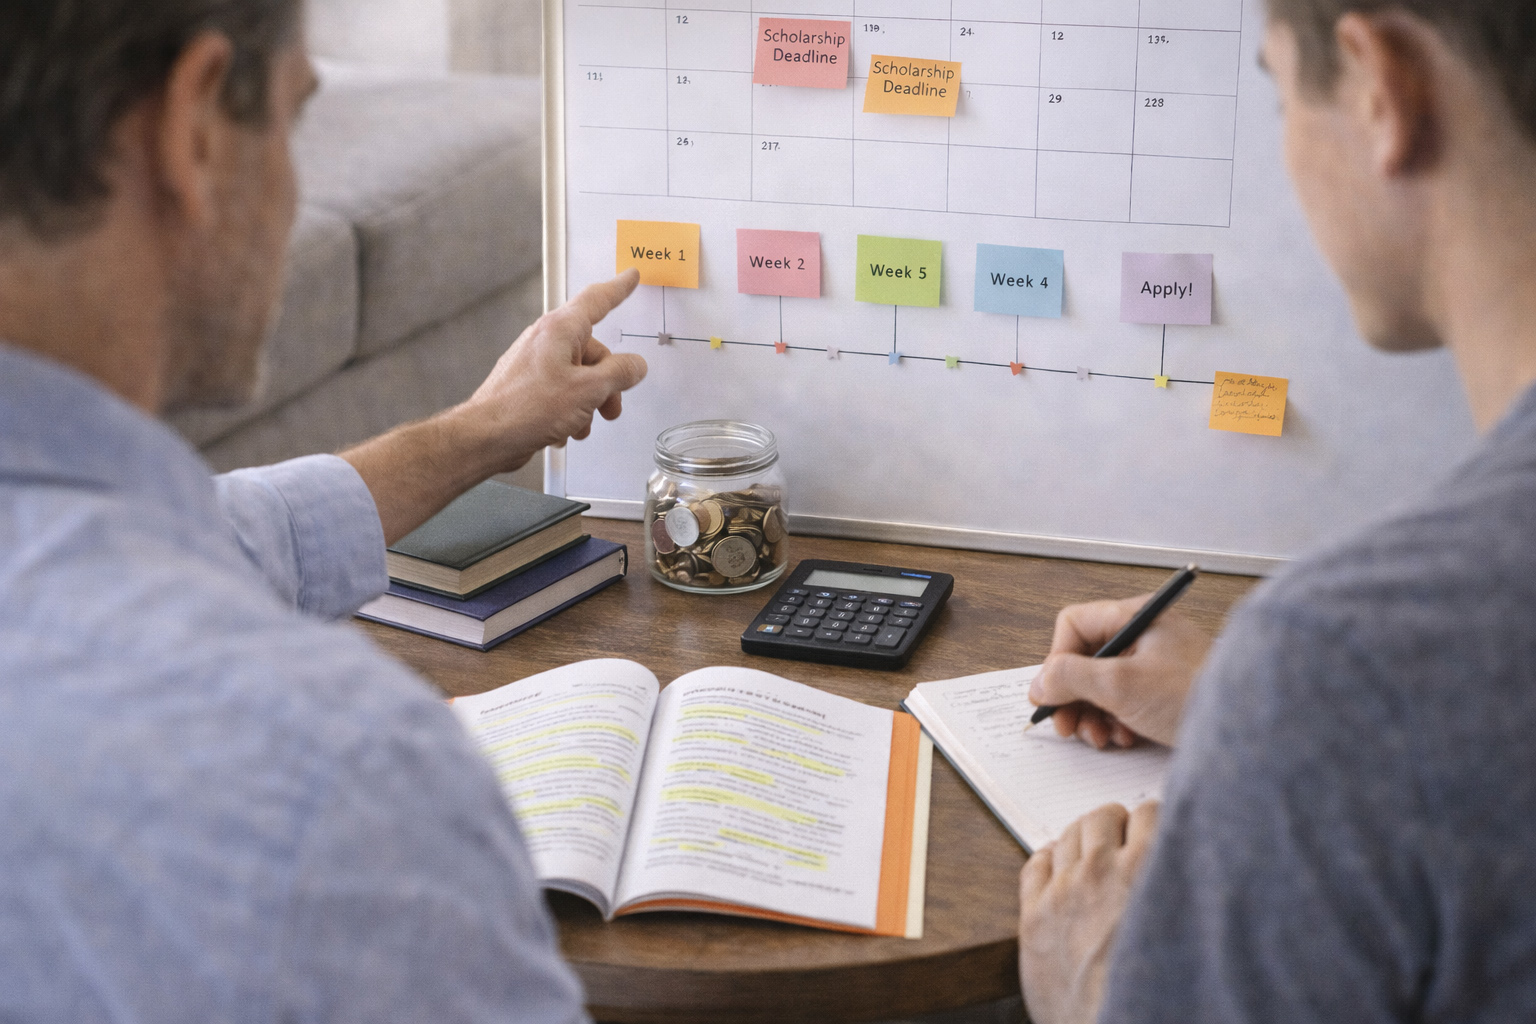
Combine multiple funding sources rather than relying on a single channel to increase resilience. Typical options include savings plans, scholarships, grants, work-study, and manageable borrowing when needed. Each option has trade-offs in terms of availability, flexibility, and future obligations, so map them against your priorities. A mix of grants and targeted savings often minimizes long-term financial strain.
- Explore merit and need-based aid early.
- Investigate employer tuition assistance or community grants.
Layering funding sources keeps monthly burdens lower and preserves emergency reserves. Diversifying reduces the chance that one setback will derail the entire plan.
Practical Savings and Spending Strategies
Adopt concrete habits that support steady progress toward education goals without sacrificing current stability. Automate small, regular transfers to a designated fund, and review recurring expenses to free up incremental savings. Encourage part-time work or internships that build skills and offset costs, balancing workload with study demands. Prioritize cost-effective choices such as used textbooks, shared housing, or online courses where quality and outcomes align.
Small, consistent changes compound over time and create options when unexpected expenses appear. Building habits is as important as the initial funding decision.
Conclusion
Balancing education expenses requires a mix of realistic budgeting, diversified funding, and adaptable habits. Regularly revisiting priorities and options keeps the plan aligned with changing needs. With a clear, flexible approach, funding education becomes manageable rather than stressful.