
Education expenses rarely arrive on a neat schedule, and the choices families make early on affect options later. A progressive spending plan treats costs as a series of decisions rather than one large bill, helping households keep learning affordable without cutting opportunities. This approach blends clear priorities, mixed funding sources, and small ongoing habits that reduce pressure when tuition or program fees spike. The goal is a plan that adapts as needs change instead of collapsing under one unexpected semester or certification cost.
Set realistic priorities and timelines
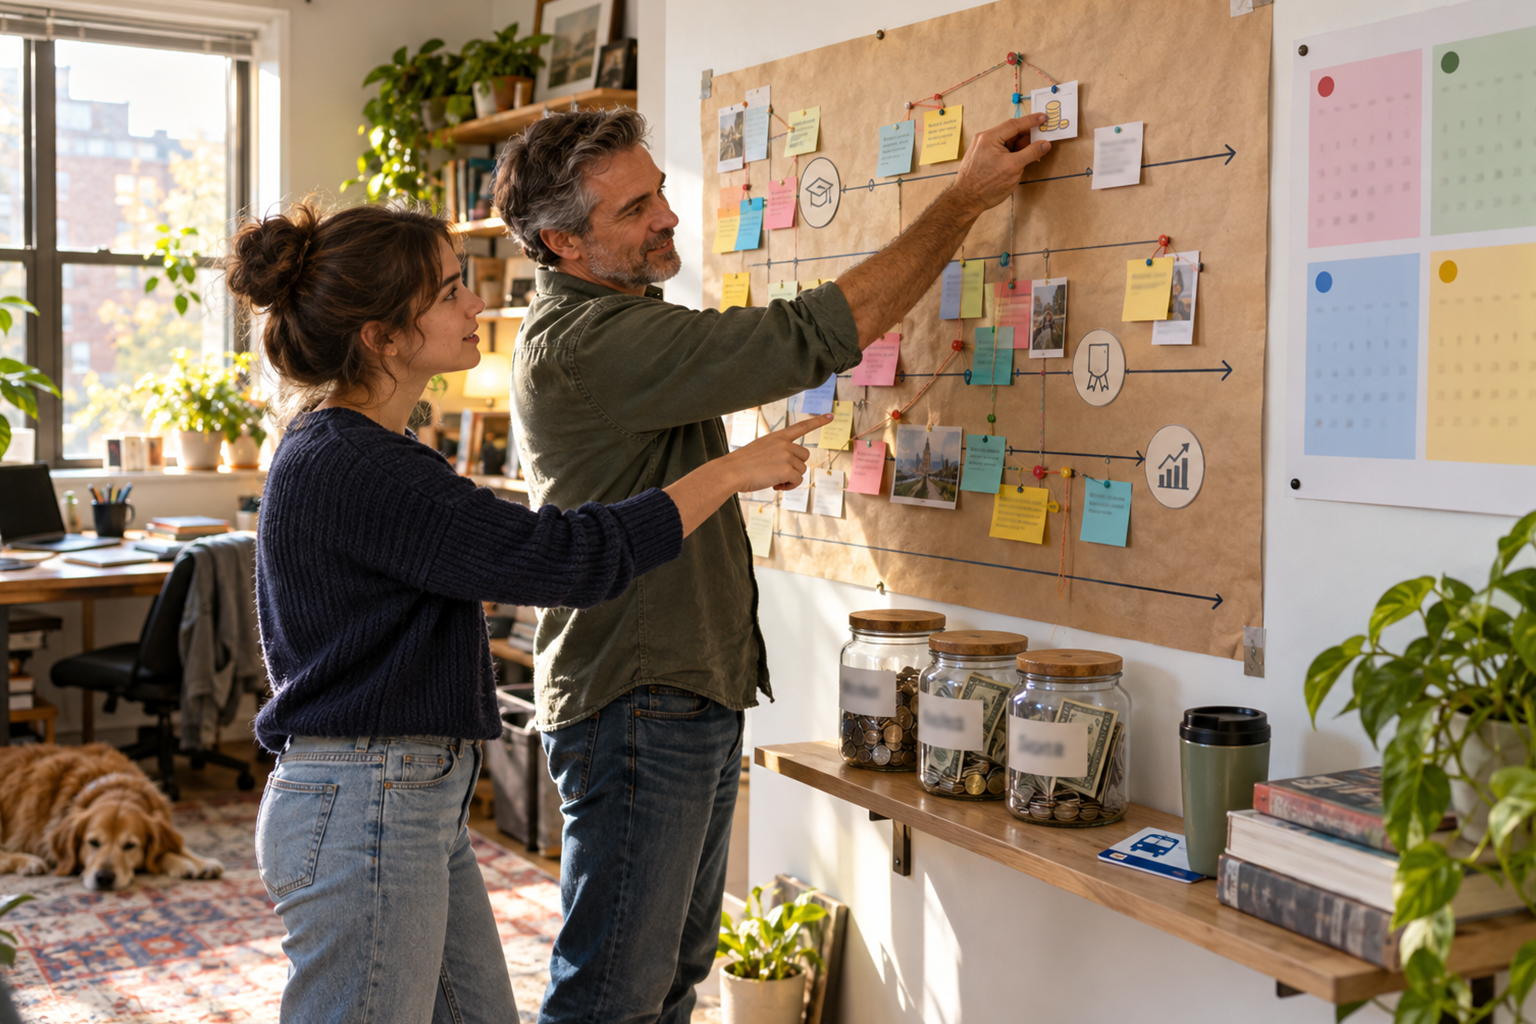
Start by listing goals and assigning timelines: short workshops, multi-year degrees, or recurring certification costs each demand different treatment. Rank what matters most — program quality, networking opportunities, or speed of completion — and let that order guide spending. When families agree on priorities, it’s easier to say yes to one option and no to another without second-guessing. Clear timelines also reveal when to save more aggressively or when to rely on income instead of loans.
Use timelines to avoid last-minute borrowing. Small, planned contributions reduce the need for emergency solutions and keep interest costs lower over time.
Combine small savings and targeted cuts
Rather than searching for a single large saving, look for many modest reductions that add up. Swap pricier electives for reputable online equivalents, negotiate installment plans with schools, or choose used textbooks and shared resources. Evaluate nonessential expenses across a term and redirect those dollars to tuition or fees most likely to increase over time. These smaller moves preserve learning quality while trimming total outlay.
Targeted cuts protect core experiences while freeing funds for unavoidable costs. They also create a buffer that absorbs price increases without drastic lifestyle changes.
Use flexible funding and review regularly
Mix short-term savings, dedicated accounts, payment plans, and modest borrowing so funds remain flexible as needs shift. A dedicated balance for education that allows partial withdrawals and easy top-ups works better than rigid accounts that penalize changes. Regular reviews—at least twice a year—catch creeping costs, update priorities, and reallocate surplus money to the next expense. Treat reviews as practical check-ins, not reasons for guilt.
Flexibility reduces the chance a new fee forces a rushed decision. A simple quarterly review keeps the plan honest and responsive.
Conclusion
A progressive spending plan turns education costs into manageable, intentional choices. Small, consistent actions and periodic reviews prevent surprises and preserve options. Over time this approach keeps learning affordable without sacrificing quality.