
Education costs don’t have to be a source of constant worry; small, deliberate choices can reduce pressure without sacrificing opportunity. Start by figuring out what matters most for your learner and when the big expenses will hit the budget. Knowing the timeline—upcoming tuition, materials, or exams—lets you concentrate savings and avoid last-minute debt. This piece offers practical steps families can apply immediately and adapt as needs change.
Prioritizing Goals and Timelines
Begin with a short checklist: what programs are non-negotiable, which could wait, and which offer the most long-term value. Distinguish one-time costs like enrollment fees from recurring items such as monthly tutoring or subscription services. Assign a rough timeline and amount to each priority so you can target savings and decide which payments are flexible. This clarity makes trade-offs easier to accept and helps keep spending aligned with real outcomes.
Revisiting priorities each semester or year keeps plans realistic as circumstances shift. A clear timeline also improves conversations with family members who contribute financially.
Everyday Choices That Add Up
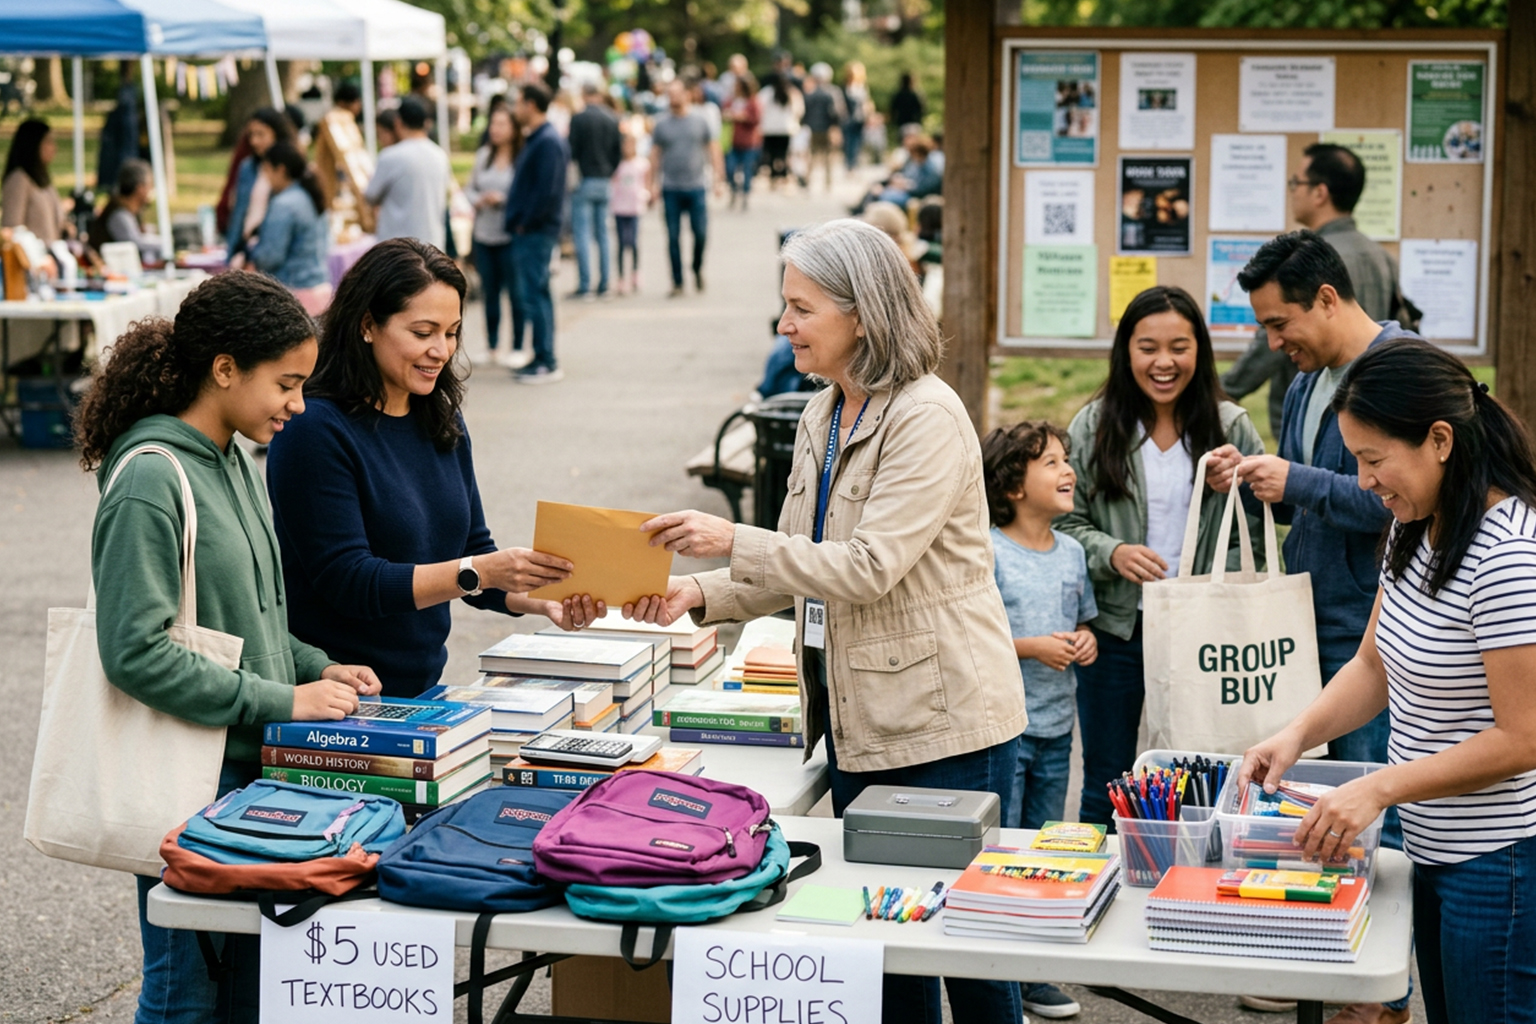
Small changes in routine spending quickly compound when applied consistently. Review subscriptions and cancel unused platforms, compare secondhand textbooks or digital rentals, and coordinate bulk purchases of supplies to capture discounts. Allocate a specific allowance for optional extras like clubs or field trips so choices are made deliberately instead of impulsively. These modest habits reduce leakage in the household budget while preserving core learning investments.
- Buy used or earlier-edition textbooks for non-core classes.
- Share costs for group materials with classmates.
- Use community resources for labs, libraries, or practice spaces.
- Schedule tutoring strategically around problem areas rather than open-ended sessions.
Over time these adjustments free up funds for higher-impact expenses, and they teach students how to weigh costs against benefits. Keeping the list short helps sustain changes.
Leveraging Institutional and External Support
Explore every official pathway that trims bills: institutional scholarships, fee waivers, payment plans, and employer tuition benefits can substantially lower out-of-pocket costs. Reach out to financial aid offices and counselors early so you know deadlines and required documentation. Community organizations and civic groups sometimes offer awards or vouchers for supplies and exam fees as well. Combining several modest supports often matches or exceeds the impact of a single large savings effort.
Being proactive pays: applications submitted on time and a clear case for need can unlock resources many families overlook. Periodically check for new opportunities as programs change.
Planning Tools and Regular Review
Set up a simple tracking system—a spreadsheet or a budgeting app—to record education-related flows and upcoming commitments. Include estimates for inflation in recurring costs and update figures after each term so the plan stays accurate. Small automatic transfers to a dedicated education savings account smooth out peaks and make mid-year surprises manageable. Transparency within the household about contributions and expectations eases stress and improves cooperation.
Make it a habit to review the plan quarterly and adjust contributions or priorities as needed. That regular attention prevents surprises and keeps choices intentional.
Conclusion
Lowering education spending is often more about choices and timing than drastic cuts. Start small, use the supports available, and review plans regularly so adjustments stay practical. Over time those steady moves protect learning opportunities without overwhelming the household budget.