
Education expenses rarely arrive in neat monthly chunks — they spike with tuition, books, summer programs, and exams. Treating the year as a map makes those peaks predictable instead of painful. This piece lays out practical steps to identify when costs occur, where to trim, and how to fund the gaps without sacrificing important opportunities. Read on for a straightforward yearly approach you can adapt to any household budget.
Map the academic year
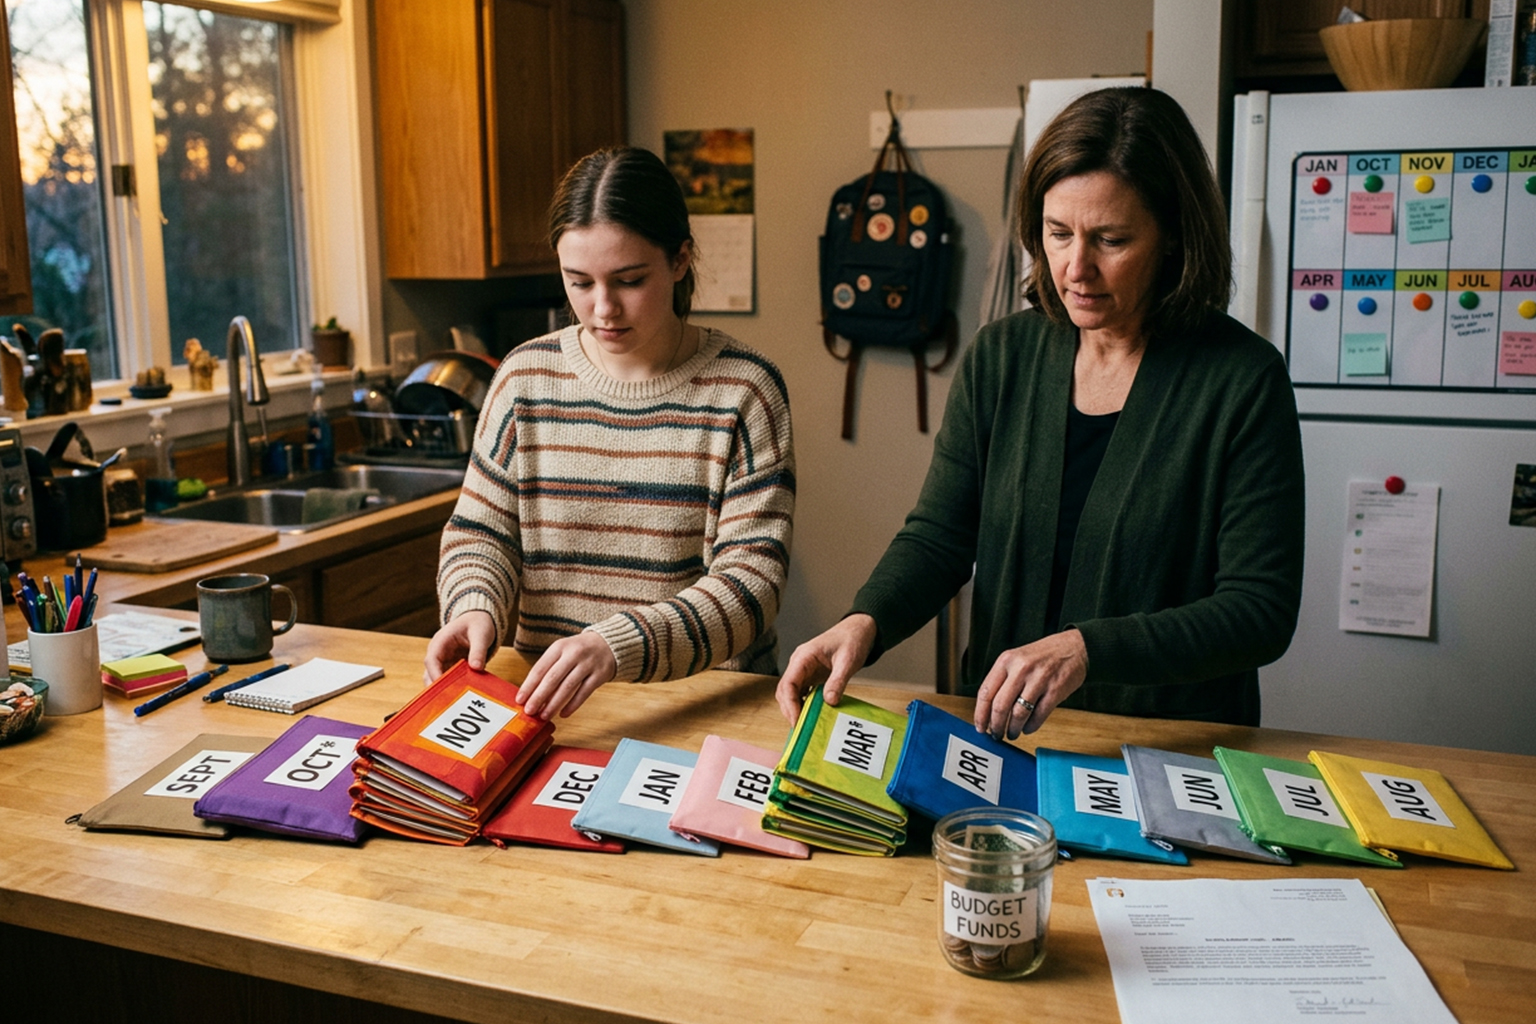
Start by listing every expected cost for the next 12 months: tuition payments, registration fees, books, supplies, field trips, uniforms, and any exam or application charges. Note due dates and group items by month so you can see which months will be tight. Include likely irregular expenses such as summer courses or certification renewals that may fall outside the typical semester schedule.
Once you have the calendar view, highlight the three worst months for cash flow. Those are the periods to plan savings and temporary adjustments rather than reacting at the last minute.
Trim and prioritize without cutting value
Not every expense needs to be equal. Decide which courses, materials, or services deliver the most long-term benefit and which are nice-to-haves. Swap brand-new textbooks for used copies, use library resources, and evaluate cheaper alternatives for software or tutoring where quality won’t suffer.
Small cuts add up: skipping one premium purchase or delaying a nonessential workshop can free money for a looming tuition bill. Prioritization keeps essential learning intact while easing the financial pinch.
Spread and shift payments
Where possible, convert one-off bills into smaller, regular payments to smooth monthly strain. Ask schools about payment plans, split costs between semesters, or align certain purchases with income timing like paydays or scholarship disbursements. For families, discuss sharing or rotating responsibilities so larger bills aren’t always shouldered by one person.
These shifts reduce surprises and make budgeting more realistic. Predictable payments are easier to absorb and less likely to force high-interest borrowing.
Fund strategically and track results
Build a small, dedicated education fund to cover predictable spikes; even modest recurring transfers add up over a year. Combine that with short-term measures such as targeted side income, scholarship searches, or selling unused items tied to education budgets. Track spending monthly so you can compare plan versus reality and adjust allocations before problems escalate.
Regular tracking turns this plan from theory into habit. Over a few cycles you’ll be able to forecast needs more accurately and reduce stress around payments.
Conclusion
Plan your year, prioritize what matters, and smooth payments to avoid crisis borrowing. Small, consistent funding moves and monthly tracking make big peaks manageable. Applied together, these steps keep education spending under control while preserving learning opportunities.