
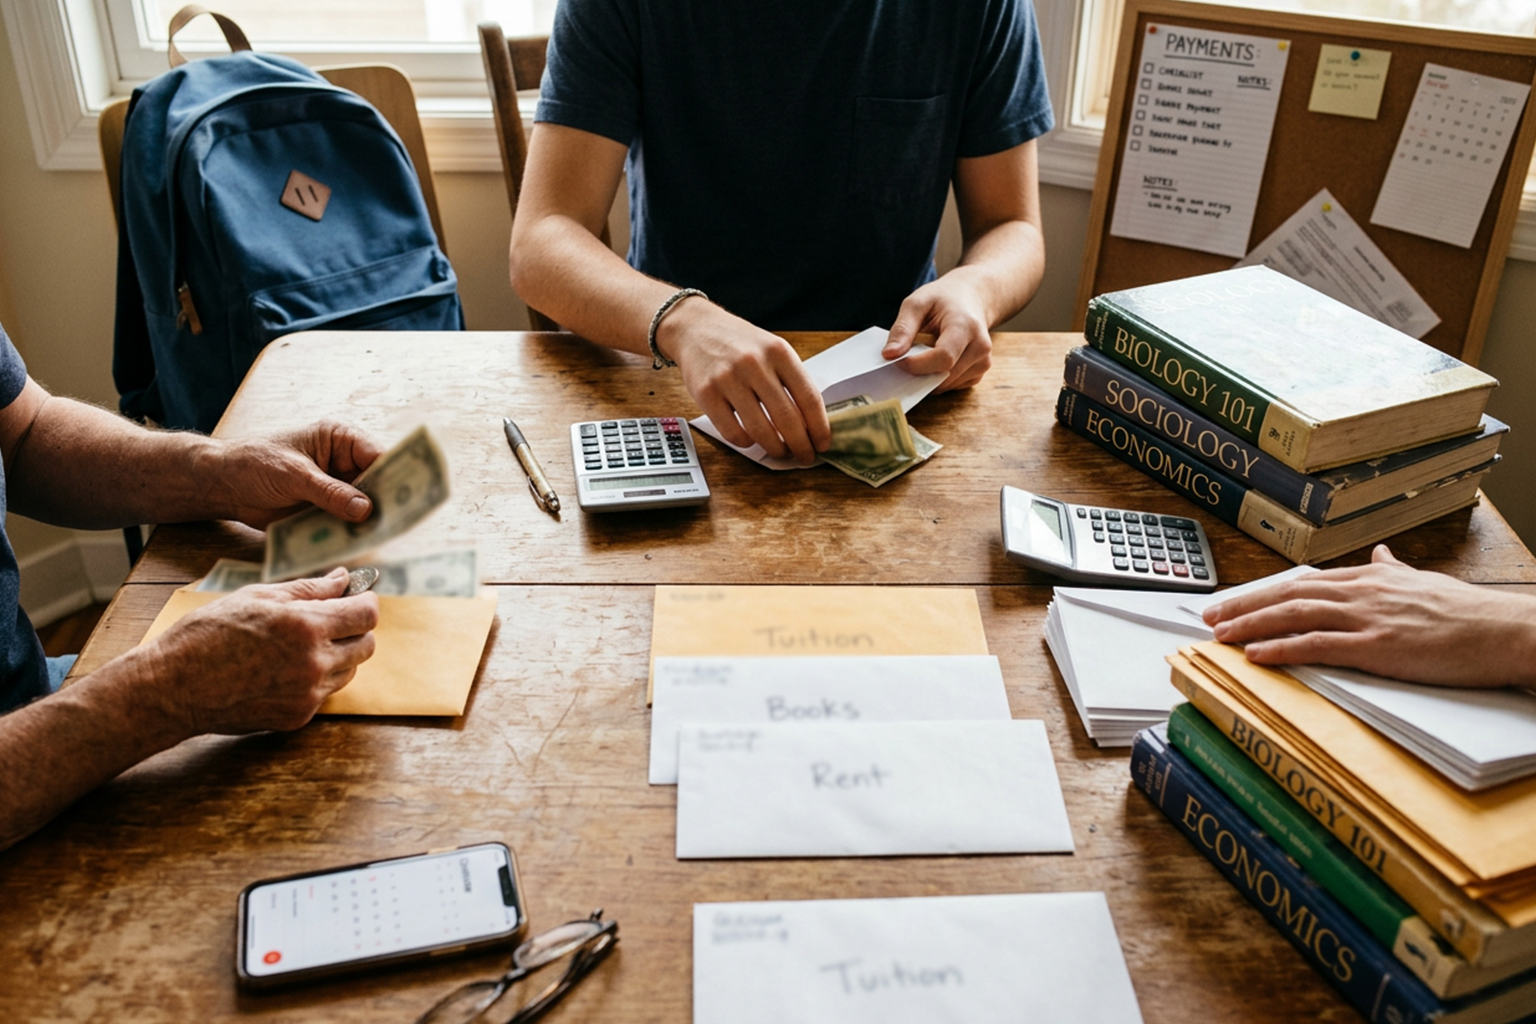
Deciding which learning expenses deserve your money is rarely simple, but a few clear priorities make choices easier. Start by separating essentials — tuition, required materials, regular fees — from optional extras like premium subscriptions or one-off upgrades. Look ahead to upcoming terms or certifications so costs don’t arrive as surprises, and build a small buffer for unexpected expenses. A calm, planned approach reduces stress and keeps your household budget intact.
Identify what truly moves the needle
Focus first on expenses that directly affect outcomes: accredited programs, required textbooks, and necessary lab or software access. These items usually have a measurable impact on completion and skill development, so they often deserve top priority in your spending plan. For optional services, compare cost against likely benefit — for example, is a private tutor the fastest path to a credential you need? Make choices based on what will realistically improve results, not on perceived prestige.
Trim lower-impact spending before cutting essentials. That way your core progress remains uninterrupted while you free up funds for high-value opportunities.
Use flexible tactics to stretch funds
Timing purchases, taking advantage of secondhand books, and choosing open-source or institutional software alternatives reduce recurring costs without harming learning. Consider part-time study, employer tuition assistance, or apprenticeships that combine income with training so you pay less out of pocket. Small monthly savings in daily life — packed lunches, shared subscriptions, or deliberate entertainment choices — add up over a semester.
Regularly revisit these tactics; what helps one term may be less useful the next, so keep flexibility in your plan.
Plan funding with short-term and long-term lenses
Match funding sources to the timeframe of the expense: emergency savings for immediate needs, monthly budgets for recurring items, and targeted savings or investment accounts for multi-year programs. If borrowing becomes necessary, compare interest rates, repayment terms, and whether the loan affects future borrowing capacity. For families, transparent conversations about shared responsibility and realistic expectations prevent friction and ensure everyone understands priorities.
Document your plan in simple terms: what you’ll pay, when you’ll pay it, and what you’ll postpone. Clarity reduces impulse decisions and keeps education on track.
Conclusion
Prioritize spending that advances completion and employment prospects, and reduce or delay lower-impact costs. Blend short-term fixes with longer funding choices to avoid surprises and maintain momentum. Small, consistent planning choices protect both learning goals and your household budget.