
Education costs can feel like a moving target, growing faster than many household budgets. Break the problem into parts and you’ll see where meaningful savings are possible. Small shifts—choosing where to take classes, when to buy materials, how to plan payments—add up over time. This piece focuses on practical, repeatable steps families and adult learners can use to reduce spending without cutting value.
Set a realistic budget and revisit it
Start by listing every expected expense for the next year: tuition or course fees, books and supplies, transportation, housing if applicable, and any regular technology costs. Assign priorities to each item so you know what’s essential versus negotiable when money gets tight. Track actual spending for several months to catch one-off fees and seasonal spikes you might have missed. Build in a conservative estimate for price increases on recurring items.
Review this budget quarterly, and adjust when circumstances change, like a new scholarship, a schedule shift, or a change in living arrangements. Treat the plan as a living tool rather than a constraint.
Cut costs smartly: choices that matter
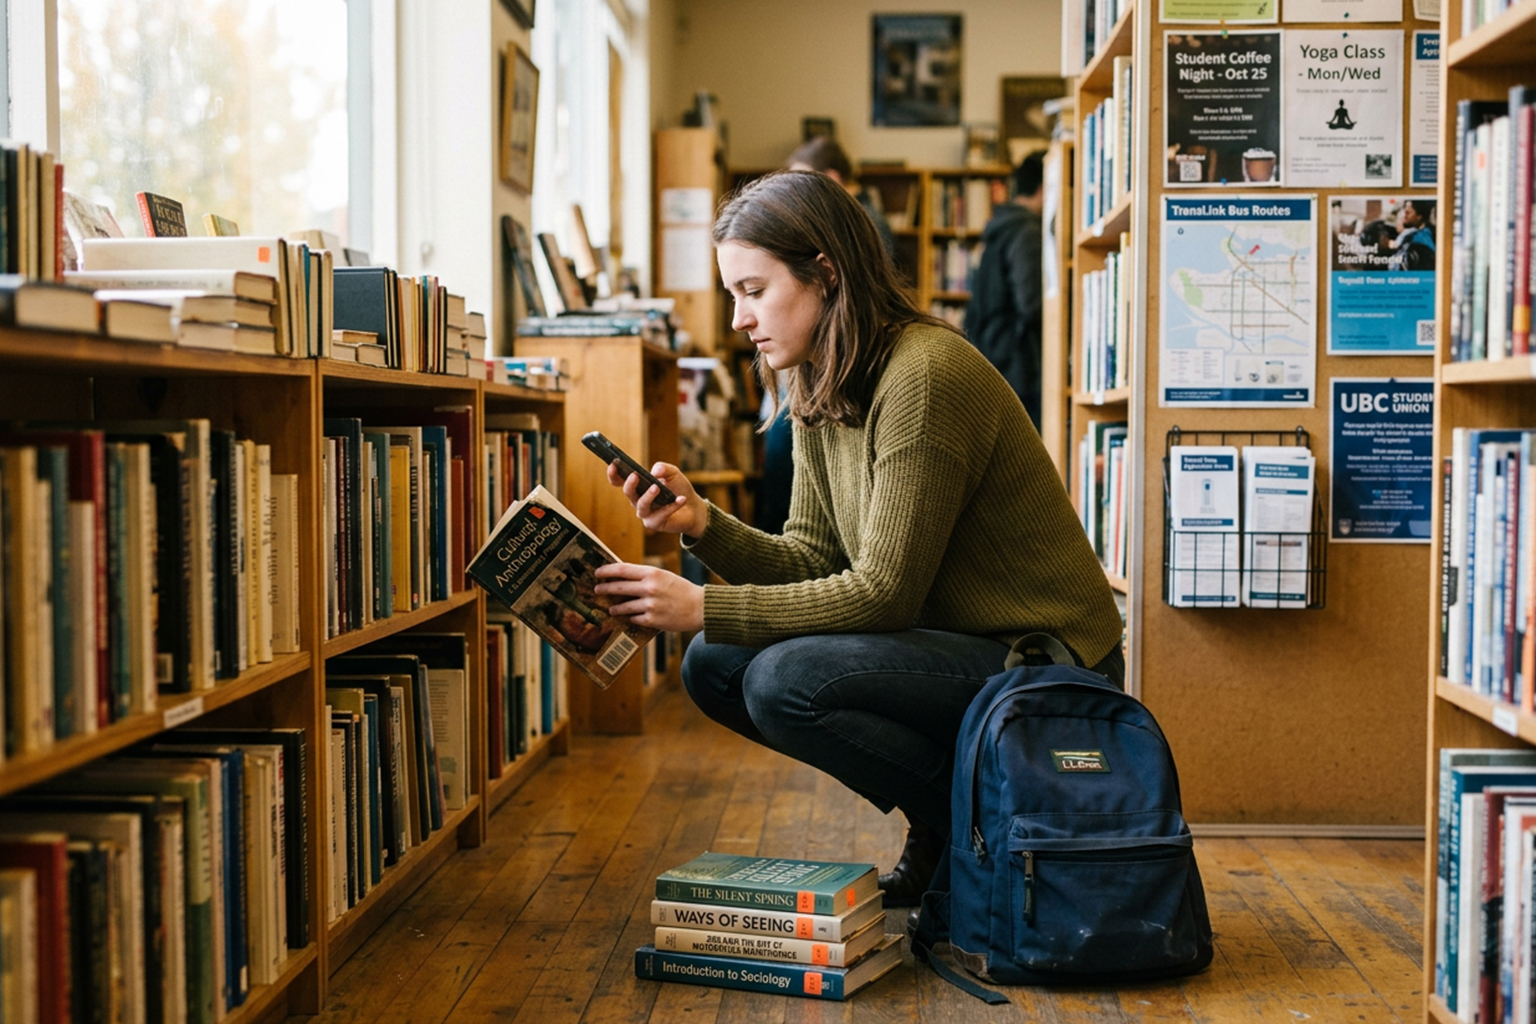
Not all savings are equal—focus on moves that preserve learning outcomes while lowering expenses. Consider earning general credits at lower-cost providers, choose digital or used course materials, and evaluate the total cost of attendance including hidden fees. Use institutional resources: advisors, bookstore discounts, and employer tuition programs can remove or reduce big line items. Think beyond textbooks: shared housing, public transit passes, and meal planning often shave more than a single coupon ever will.
- Buy used or digital textbooks; sell them after the term.
- Take prerequisite or general-education classes at less expensive schools.
- Tap scholarships, grants, and one-off awards—small dollars add up.
- Ask employers about tuition assistance or flexible scheduling to keep income steady.
Adopt a few of these tactics rather than chasing every tip; targeted changes are easier to maintain and compound into real savings. Keep receipts and notes so you can repeat what works next semester.
Plan for peaks and protect your progress
Many families underestimate intermittent costs: lab fees, field trips, technology upgrades, or certification tests. Build a small buffer or short-term savings account to cover these predictable spikes so they don’t derail your semester. Also plan for life changes—a move, a job loss, or health needs—by keeping an emergency fund separate from education savings. Where possible, stagger payments or negotiate installment plans with schools to smooth cash flow.
Consistent monitoring and small, proactive funds protect progress and reduce stress. That stability makes it easier to stick with the program and reach long-term learning goals.
Conclusion
Reducing education expenses is a mix of planning, selective choices, and simple habits. Focus on the highest-impact moves, keep the budget current, and protect against surprises. Steady, sensible adjustments preserve opportunity while easing the financial load.